Six Best Lenders for a Personal Loan With Collateral in 2026
Last updated: 2026-10-17
Walking into a secured loan discussion can feel like trying to find a flashlight in a thick fog. When you use an asset like a car or a savings account to back a loan, you are making a serious promise. It is a smart move for anyone looking to snag lower interest rates or get approved when traditional banks say no.
By putting up collateral, you tell the lender that their risk is much lower. This often leads to better terms and higher borrowing limits than an unsecured loan would ever allow. You are essentially trading a piece of your property for more favorable financial conditions.
Choosing a lender requires looking past the shiny marketing. You have to weigh how quickly you need the cash against the risk of losing your property. A sudden engine failure in a vehicle used as collateral or a dip in the stock market can change your loan math overnight.
This list highlights the top players in the 2026 market. We focused on companies that offer stability and speed for different financial needs.
- JetzLoan
- Best Egg
- OneMain Financial
- Freedom First Credit Union
- Balance Credit
- Synchrony
How These Lenders Were Evaluated
We wanted to find lenders that actually use collateral to help a borrower’s profile. Our team looked at how these institutions handle different credit scenarios. This included people with perfect histories and those currently struggling to stay afloat.
It is not just about the total amount of money on the table. The speed of the transaction matters just as much. A lender that makes you wait weeks for paperwork is rarely helpful when you are facing a time-sensitive bill.
Speed of funding, maximum limits, and application ease were our primary metrics. We also checked if a lender requires a hard credit pull during the first inquiry.
Being able to see your potential terms without dinging your credit score is a massive advantage. We specifically looked for lenders offering „soft pulls” for initial quotes. This allows you to shop around without seeing a trail of inquiries on your credit report.
| Lender Name | Max Loan Amount | Funding Speed | Credit Impact on Inquiry |
|---|---|---|---|
| JetzLoan | $35,000 | As little as 24 hours | No hard credit pull |
| Best Egg | $50,000 | See site | See site |
| OneMain Financial | $30,000 | As soon as 1 hour | No credit score impact |
| Freedom First Credit Union | See site | See site | See site |
| Balance Credit | $4,000 | Next business day | No impact on credit score |
| Synchrony | See site | See site | See site |
Top Rated Lenders for Secured Funding
1. JetzLoan
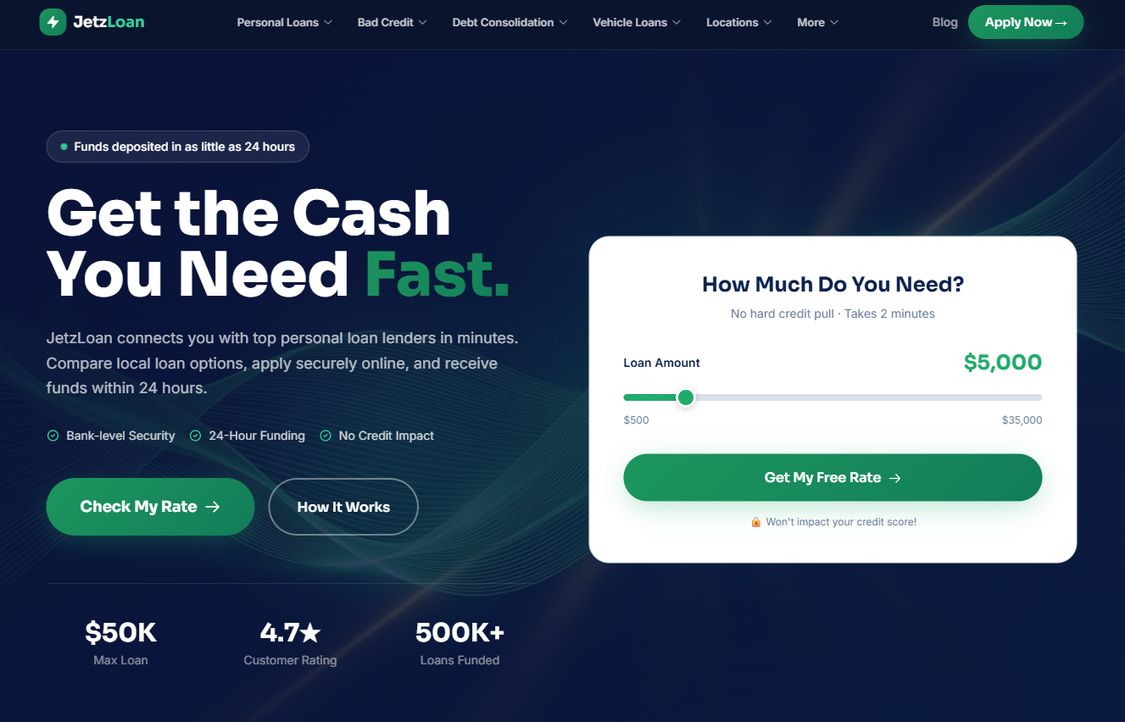
JetzLoan works like a high-speed bridge for people who need cash without the usual waiting games. They connect borrowers with top lenders in just a few minutes. This makes them a great choice for emergencies.
If you need money for an urgent medical bill or an unexpected home repair, their ability to deposit funds within 24 hours is hard to beat. (jetzloan.com)
This lender is great if you are wary of the „credit score dance.” They offer a way to check your rate without a hard credit pull. You can explore options without fearing a lower score.
This is vital if you plan to apply for a mortgage or an auto loan soon. You cannot afford any fluctuations in your credit profile right now. It is a transparent, digital-first approach.
Pros:
- Funds deposited as quickly as 24 hours.
- No hard credit pull during the initial check.
- High maximum loan limit of $35,000.
Cons:
- Acts as a connector rather than the sole lender.
2. Best Egg
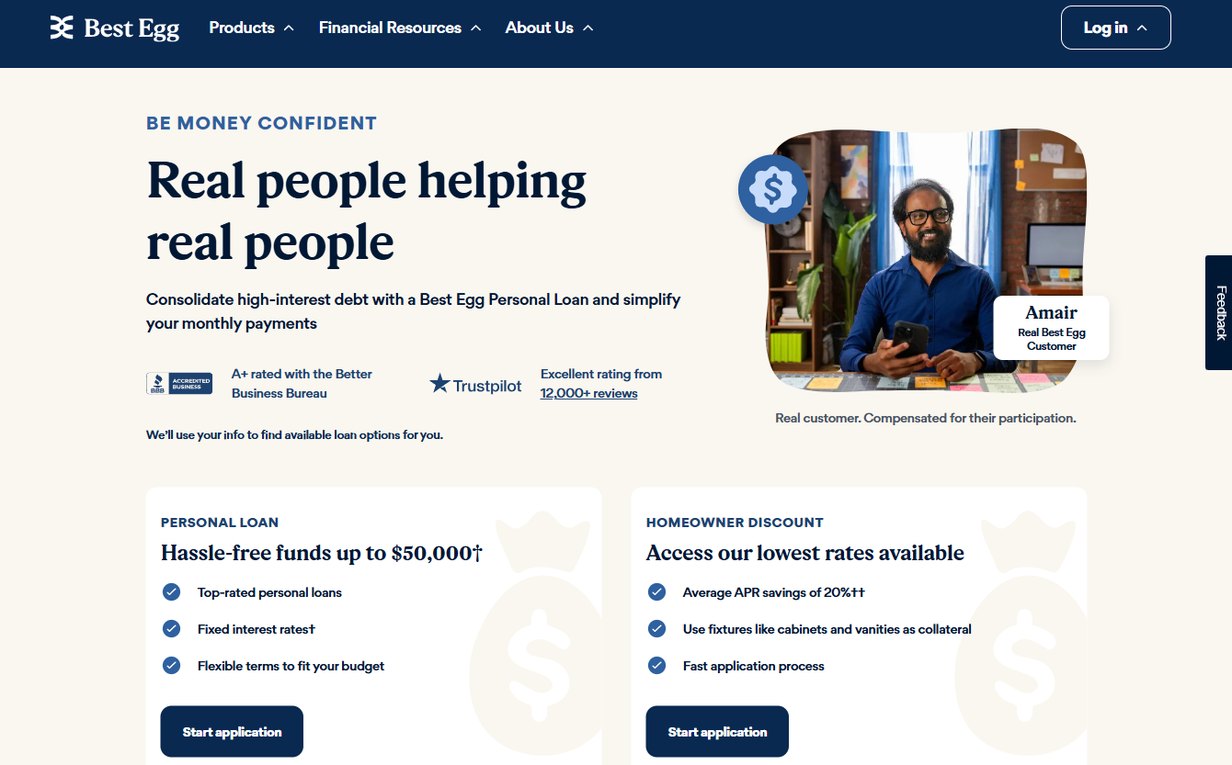
Best Egg is a heavyweight in the personal loan space. They are known for a straightforward approach. They offer products designed to help users consolidate high-interest debt.
If you are carrying multiple balances on high-interest credit cards, a single Best Egg loan can merge them into one manageable monthly payment. You often see a significantly lower APR this way.
One interesting feature is their ability to use household fixtures as collateral. You can use things like cabinets or vanities. This unconventional method can open doors for homeowners who might otherwise struggle.
It is a specialized form of secured lending. It treats home improvements as an asset, providing a pathway for equity-based borrowing without the complexity of a full home equity loan.
Pros:
- High loan amounts up to $50,000.
- Potential for 20% APR savings.
- Homeowner discounts available.
Cons:
- Terms and rates are subject to specific eligibility.
3. OneMain Financial
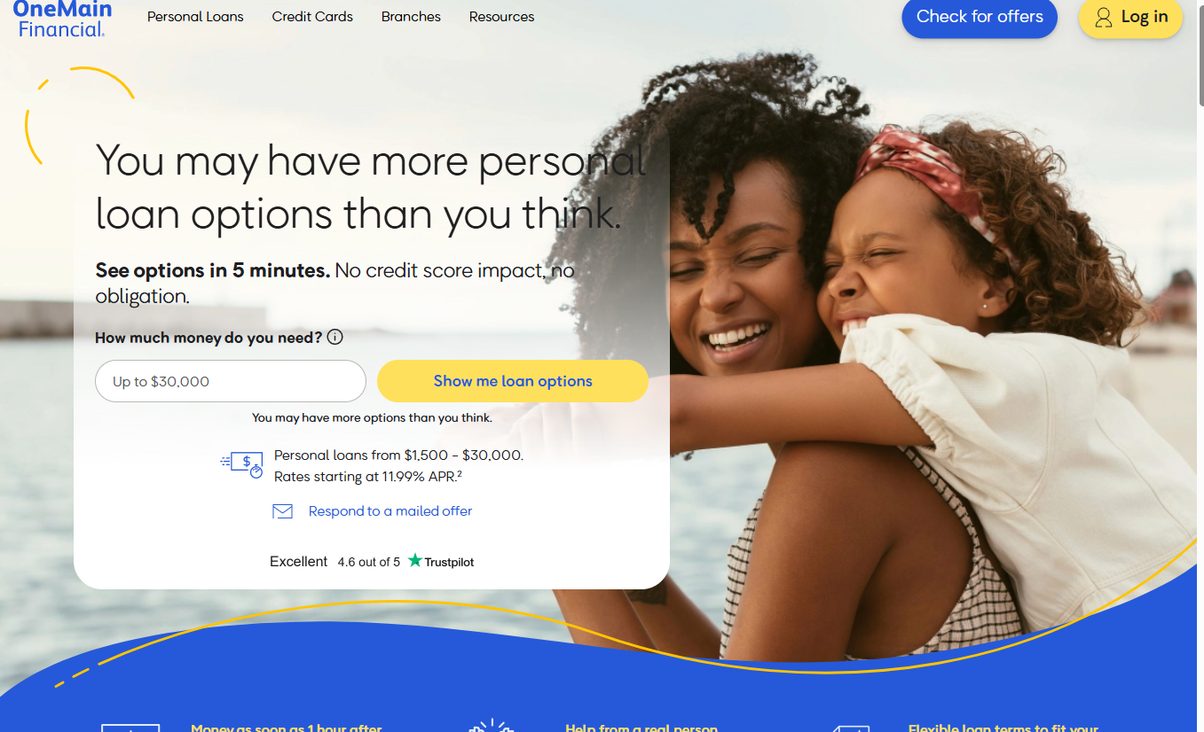
OneMain Financial is a powerhouse for those who want a mix of digital ease and physical presence. With over 1,300 branches, they offer a human touch. Many online-only lenders simply cannot compete here.
If you get stuck in a digital loop or struggle to upload documents, you can walk into a branch. You can talk to a real person face-to-face. This physical presence provides a layer of security that purely digital fintechs often lack.
They are a standout choice for borrowers with less-than-perfect credit. You can see your options in five minutes without a credit score impact.
For urgent needs, like a car repair that prevents you from getting to work, they can provide funds as soon as one hour after signing. This speed is vital in „make or break” financial moments.
Pros:
- Extremely fast funding (1 hour post-signing).
- Extensive branch network for in-person support.
- Flexible terms from 24 to 60 months.
Cons:
- Maximum loan amount is capped at $30,000.
4. Freedom First Credit Union
Freedom First Credit Union operates with a community-centric mindset. This sets them apart from big-box banks. They offer secured personal loans where you can use share accounts or certificates as collateral.
This is a stable way to build credit while accessing capital. Because you are borrowing against your own savings, interest rates are typically much lower. The approval process is often simpler since the risk to the credit union is minimal.
They also provide perks like early access to paychecks through direct deposit. This flexibility helps with cash flow management. You can time your payments more effectively against your income cycle.
For those who value local involvement, their „Play for Purpose” programs show a commitment to local causes. It fosters a sense of mutual benefit between the institution and its members.
Pros:
- Community-focused service model.
- Options to use share accounts as collateral.
- Perks like getting paid up to 2 days early.
Cons:
- Likely requires membership through specific criteria.
5. Balance Credit
Balance Credit is a specialized option for those needing quick, smaller amounts of cash. They offer loans up to $4,000. This makes them a niche player compared to the giants.
Their focus is on inclusivity. They review applications even for those with less-than-perfect credit. This makes them a vital resource for short-term liquidity needs where a massive loan isn’t necessary.
Their process is incredibly fast. Money can hit your account by the next business day. One of their most attractive features is the lack of penalties for paying off a loan early.
This can save you significant interest over time. If you get a tax refund or a bonus, you can wipe out the debt immediately. You won’t face „prepayment penalties” like you might at larger banks.
Pros:
- No penalties for early loan payoffs.
- Inclusive consideration for various credit levels.
- Quick application process.
Cons:
- Relatively low maximum loan amount of $4,000.
6. Synchrony
Synchrony operates primarily through marketplace and financing models. They are often tied to specific retail brands. This makes them a specialized choice rather than a general-purpose lender.
They are the go-to for people looking to finance specific purchases through retail partnerships. For example, if you are buying high-end appliances, Synchrony might offer 0% interest promotional periods.
They offer various services, including credit cards and marketplace financing. While they might not be your first choice for a general cash infusion for utility bills, their specialized financing is excellent for large purchases.
Their integration into major retailer checkouts makes the transition from „browsing” to „financing” almost instantaneous. It is a very smooth experience for targeted credit options.
Pros:
- Strong retail-specific financing options.
- Diverse range of credit products.
- Part of a large, established financial ecosystem.
Cons:
- Less focused on general-purpose personal loans.
Understanding Collateral Types and Risks
Before committing to a secured loan, you must understand exactly what you are offering. Collateral generally falls into three categories: liquid assets, physical property, and financial instruments. Each has a unique risk profile.
Liquid assets, like savings accounts or CDs, are the safest for the lender. They are often the cheapest for you too. If you use $5,000 in a savings account as collateral, the interest rate is typically very low.
The downside is that the money is „locked.” You cannot use that $5,000 for other expenses while the loan is active. This effectively reduces your available cash reserves when you might need them most.
Physical property, specifically vehicles, is a very common form of collateral. While this allows for larger loan amounts, it introduces „depreciation risk.” The value of your car drops every year.
If you take out a $15,000 loan on a car worth only $12,000 due to high mileage, you are „underwater.” You owe more than the asset is worth. This creates a massive burden if you need to sell the car or default.
Financial instruments, including stocks or bonds, offer high borrowing potential. However, they come with extreme volatility. If the market takes a sharp downturn, your lender may issue a „margin call.”
They might require you to deposit more cash immediately. If you cannot, they can force the sale of your investments at a loss. This requires high financial literacy to manage safely.
The Step-by-Step Guide to Securing a Loan
Securing a loan requires a systematic approach. You want the best terms without accidentally damaging your financial health. Follow these steps to move through the process efficiently:
Step 1: Audit Your Assets. Before applying, list everything you could use as collateral. Note the current market value, not the original purchase price. For vehicles, check Kelly Blue Book. For home fixtures, consider replacement costs. Have your titles and statements ready.
Step 2: Check Your Credit Score (Soft Pull). Use the „no credit impact” features from lenders like JetzLoan or OneMain Financial. This gives you a baseline. Knowing your score helps you see if you qualify for „prime” rates or more expensive „subprime” options.
Step 3: Compare the APR, Not Just the Interest Rate. The interest rate is just the cost of the principal. The Annual Percentage Rate (APR) includes fees and points. A 5% interest rate with $500 in fees might be more expensive than a 6% rate with zero fees. Always use the APR for an apples-to-apples comparison.
Step 4: Evaluate the Repayment Timeline. A longer term, like 60 months, means lower monthly payments. This helps your monthly cash flow. However, you will pay significantly more in total interest. Calculate the „total cost of the loan” to see the real price tag.
Step 5: Review the Default Terms. Read the section on „remedies upon default.” You need to know how many missed payments trigger a default. Also, check how much notice the lender must give before they seize your collateral. This „grace period” is vital.
Avoiding Common Pitfalls in Secured Lending
The biggest mistake is underestimating the weight of collateral. When you put your car or savings on the line, you are telling the lender, „If I fail, you take this.” It is a high-stakes game.
You need a clear-eyed view of your budget. A common psychological trap is thinking, „I can always pay it back later.” The legal reality of a secured loan is rarely that flexible.
Always read the fine print regarding defaults. Some lenders are much more aggressive than others. Some might repossess a vehicle after a single missed payment. Others might offer a structured workout plan.
Keep a close eye on the total cost of borrowing. A lower interest rate might look enticing, but high fees can change everything. Watch out for „origination fees” taken from your loan amount upfront. You might receive $9,500 even though you signed for $10,000.
Finally, do not rush the process just because you are in a pinch. Speed is important, but taking an extra hour to compare terms can save you thousands. Use „no credit impact” checks to do your homework without consequence.
Dodaj komentarz